
First-Time Home Buyer Incentives Guide for Toronto (416)
If you're buying your first home in Toronto, a handful of federal, provincial, and municipal programs can meaningfully shrink your upfront costs — from the First Home Savings Account (FHSA) and RRSP Home Buyers' Plan (HBP) for your down payment, to land transfer tax rebates worth up to $8,475 in the City of Toronto alone. This guide walks Toronto (416) first-time buyers through each program, how they stack together, and what "first-time buyer" actually means for eligibility purposes.
The First Home Savings Account (FHSA)
The FHSA is a registered account designed specifically to help Canadians save for a first home, combining the best features of an RRSP and a TFSA: contributions are tax-deductible, and qualifying withdrawals for a first home purchase are completely tax-free.
Annual contribution limit: $8,000 per year.
Lifetime contribution limit: $40,000 per individual.
Tax treatment: contributions are tax-deductible (like an RRSP), and withdrawals used for a qualifying first home purchase are tax-free (like a TFSA) — you get both benefits with no offsetting downside.
Unused room: unused annual contribution room generally carries forward, so if you don't contribute the full $8,000 in a given year, you can catch up in a future year, up to the lifetime cap.
Because contributions are tax-deductible, opening an FHSA as early as possible — even with modest contributions — starts the clock on your lifetime room and can lower your taxable income in years you contribute.
The RRSP Home Buyers' Plan (HBP)
The Home Buyers' Plan lets you withdraw funds from your RRSP to buy or build a qualifying first home, without paying tax on the withdrawal at the time — provided you repay it on schedule.
Withdrawal limit: up to $60,000 per individual.
Repayment requirement: the withdrawn amount must be repaid to your RRSP over 15 years, starting the second year after the withdrawal. Any year you miss the required repayment, that portion is added to your taxable income for the year.
Funds must already exist: unlike the FHSA, the HBP draws on RRSP savings you've already accumulated — it doesn't create new contribution room, so it works best if you've been contributing to an RRSP for some time before buying.
Using FHSA and HBP Together
These two programs are not either/or — a first-time buyer can use both at the same time, which significantly increases the funds available for a down payment.
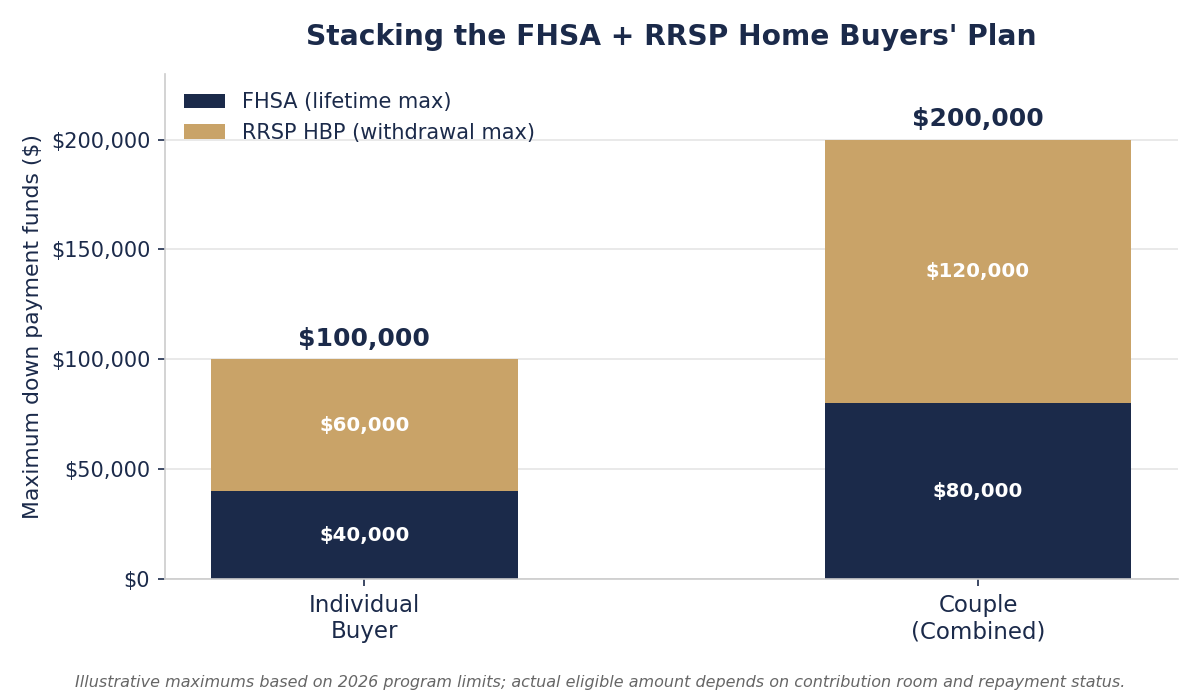
Individual buyer: up to $100,000 combined ($40,000 FHSA lifetime maximum + $60,000 HBP withdrawal maximum).
Qualifying couple buying jointly: up to $200,000 combined, by combining both partners' FHSA and HBP room ($100,000 each).
For many Toronto first-time buyers, stacking the FHSA and HBP is the single biggest lever for boosting a down payment — particularly relevant in a market where larger down payments can mean avoiding CMHC default insurance premiums or qualifying more comfortably under the mortgage stress test.
Illustrative maximums based on 2026 program limits. Actual eligible amounts depend on your contribution room and repayment status — confirm your specific numbers with a mortgage or tax professional.
Land Transfer Tax Rebates for First-Time Buyers in Toronto
Toronto is one of the only places in Canada where buyers pay both a provincial land transfer tax (LTT) and a separate municipal land transfer tax (MLTT) — but first-time buyers get rebates on both, which can add up to a meaningful combined credit.
Ontario LTT first-time buyer rebate: up to $4,000, applied against the provincial land transfer tax owing on closing.
Toronto MLTT first-time buyer rebate: up to $4,475, which covers the full municipal land transfer tax on homes priced at $400,000 or less.
Combined maximum rebate in Toronto: up to $8,475 when both rebates are applied together.
Both rebates are typically applied directly at closing by your real estate lawyer, reducing the amount of LTT you need to pay upfront rather than requiring you to pay in full and apply for a refund later — though refund applications are available if a rebate wasn't claimed at closing.
Rebate Summary Table
Figures reflect verified 2026 rebate maximums. See our dedicated Land Transfer Tax & Closing Costs Guide for the full Toronto LTT/MLTT bracket structure.
Who Qualifies as a "First-Time Buyer"?
Eligibility rules differ slightly by program, but the general concept is consistent: you (and, for some programs, your spouse or common-law partner) must not have owned and lived in a home as your principal residence recently.
For the LTT/MLTT rebates: you generally qualify if you have never owned a home, anywhere in the world, that you occupied as your principal residence — and specifically have not owned a home you lived in during the current calendar year or the four preceding calendar years.
For the HBP: a similar "first-time in the past four years" concept applies — broadly, you (or your spouse/partner) must not have occupied a home you or they owned in the four-year period before the withdrawal, with some exceptions in cases of relationship breakdown.
For the FHSA: to open an account, you must be a Canadian resident, age 18 or older (and no older than 71 at year-end), who has not owned a home you lived in as a principal residence in the year the account is opened or the four preceding calendar years.
Because the exact rules and exceptions can get technical — especially around marital status changes, prior ownership outside Canada, or co-purchasing with a non-first-time buyer — confirm your specific eligibility with your mortgage professional, accountant, or real estate lawyer before counting on any rebate or program.
Putting It Together: A First-Time Buyer's Toolkit
Open an FHSA as early as possible to start building tax-deductible, tax-free-on-withdrawal down payment savings.
If you already have RRSP savings, factor in the HBP's $60,000 withdrawal limit alongside your FHSA.
Budget for land transfer tax at closing, but apply the Ontario and Toronto first-time buyer rebates to reduce what you actually pay — up to $8,475 combined.
Talk to a mortgage professional early about how a larger down payment from FHSA/HBP funds affects your mortgage insurance costs and stress test qualification.
Keep records of your principal residence history, since eligibility for these programs depends on not having owned and occupied a home recently.
Frequently Asked Questions
Can I use the FHSA and HBP for the same home purchase?
Yes. The two programs are designed to work together. An individual can combine up to $100,000 ($40,000 FHSA lifetime limit + $60,000 HBP withdrawal limit), and a qualifying couple can combine both partners' room for up to $200,000.
Do I have to repay FHSA withdrawals like I do with the HBP?
No. FHSA withdrawals used for a qualifying first home purchase are tax-free and do not need to be repaid. HBP withdrawals, by contrast, must be repaid to your RRSP over 15 years or the missed portion becomes taxable income.
Do I automatically get both the Ontario and Toronto land transfer tax rebates?
No — you must apply for each rebate (typically handled by your real estate lawyer at closing) and meet the eligibility criteria for each, including the principal residence history requirement. They are two separate rebates from two separate levels of government, which is why Toronto buyers can claim up to $8,475 combined.
What if my spouse has owned a home before, but I haven't?
Eligibility rules vary by program and can be affected by a spouse's or common-law partner's home-ownership history. This is one of the more technical areas of first-time buyer eligibility, so it's worth confirming your specific situation with a mortgage professional or real estate lawyer before relying on any rebate.
This guide is for general informational purposes and does not constitute legal, financial, or tax advice. Always confirm current rates and rules with a licensed mortgage professional, accountant, or real estate lawyer before making a decision.
Ready to Take the Next Step?
Create your free, secure account at www.VIPCondosToronto.net for full MLS access, real-time sold data, and (where relevant) VIP pre-construction pricing and floor plans — the same tools our team uses every day.
For personalized advice on your specific Toronto buying or selling situation, contact Frank Merigliano and the VIP Condos Toronto team directly:
Phone: 416-885-0172
Email: frank@vipcondostoronto.net
Web: www.VIPCondosToronto.net
Frank Merigliano, Team Leader / Sales Representative, VIP Condos Toronto, RE/MAX PREMIER INTERNATIONAL INC., Brokerage — licensed since 1993, with RE/MAX since 1995, and a Top 50 RE/MAX team in Canada since 2015.
Have questions?
Want to know more about First-Time Home Buyer Incentives Guide for Toronto (416)? Send me a message and I'll get back to you within 24 hours.